$100 gift card when you switch*

Find out in 15 minutes if you're paying too much for health cover

Premiums went up 4.41% this year — the biggest rise since 2017 — and the extra rebate for over-65s is being cut from April 2027. Starts at 60's free comparison service checks 600+ policy options from 10 health funds and tells you straight: switch and save, or stay right where you are.

Compare now
  • 4.8 out of 5 from 250+ Google reviews
  • 600+ policy options from 10 health funds
  • 100% free — same price as going direct
  • $100 gift card when you switch*
  • 4.8 out of 5 from 250+ Google reviews
  • 600+ policy options from 10 health funds
  • 100% free — same price as going direct
  • $100 gift card when you switch*

4.8 out of 5 from 250+ Google reviews

Why compare with Starts at 60?

We built this service with Comparify — an Australian health insurance comparison specialist that has helped thousands of people find better-value cover — because our members kept telling us the same thing: "I just want an honest comparison, without the hype."

  • 10 health funds, 600+ policy options

    One comparison across the big names and the smaller not-for-profit funds you may never have heard of.

  • Completely free

    Comparify is paid by the fund if you switch — never by you. You pay exactly what you'd pay going direct, guaranteed by the Comparify Price Promise.

  • Experienced advisors

    Melbourne-based, an average of seven years in Australian health insurance, and you get their direct number.

  • Rated 4.8 out of 5

    From more than 250 verified Google reviews.

  • Honest advice — even if that's "stay put"

    Around one in three people we speak to are told their current cover is still the best fit. If that's you, we'll say so.

Starts at 60 customers speaking with a health insurance advisor at home
A real conversation, at a time that suits youPersonal Support · Free Consultation

Your comparison journey

How it works

Three simple steps. No jargon, no paperwork, no pressure.

  1. Step 1

    Tell us a little about you

    A handful of quick questions — who the cover is for, where you live, what you've got now. About two minutes. You don't need your policy documents.

  2. Step 2

    Your advisor does the digging

    A Comparify advisor compares 600+ policy options from 10 health funds against what you actually need at this stage of life — knees, cataracts, hearing, dental — not what pays the biggest commission.

  3. Step 3

    Switch, or stay. Your call.

    We walk you through it on the phone. If you switch, we handle the paperwork with your new fund and your waiting periods carry across. If you're better off staying, we'll tell you that too.
We compare more than 600 policies from 11 health insurance brands

Breadth, not just whoever pays the most. From the big names to the not-for-profit funds that return more of your premium in benefits.

Woman at her letterbox outside her home

Three things worth knowing after 60

Health cover works a little differently once you're past 60 — mostly in your favour, and in one case, not.

Proposed change 1 April 2027

Your government rebate could soon shrink

Today the rebate steps up at 65 and again at 70. From 1 April 2027 the government has proposed removing that age-based extra, so the same policy will cost more for exactly the same cover. If you're over 65, it's the best reason in years to check you're on the right policy before it lands.

See what it means for me

No fund can charge you more for being older — or turn you away

Health insurance in Australia is community rated. Your age and your health history can't be used to price you differently, exclude you, or refuse you. That protection is the reason switching is far less risky than most people over 60 assume.

You may have already earned your loading off

If you've held hospital cover continuously for 10 years since you first took it out, any Lifetime Health Cover loading has been removed for good — and some people are still paying a premium quoted before that happened. It's a two-minute check, and we'll do it on the call.

The people on the other end of the phone

Comparify's advisors are based in Melbourne, have an average of seven years' experience in Australian health insurance, and give you their direct number — so the person you speak to first is the person you speak to next time. Their average customer is 63, which means they talk about hips, cataracts and hearing aids all day. No offshore call centre. No script.

  • 7 yrs average experience
  • Melbourne-based
  • Your advisor's direct line
  • 4.8★ from 250+ reviews
They'll tell you when a cheaper policy is a worse policy — and they're not paid more for putting you with one fund over another.

Switching without losing what you've built up

The five things long-time members worry about — and what the law actually says.

  • Your waiting periods come with you

    Waiting periods you've already served must be recognised by your new fund for anything covered at the same or a lower level.

    Protected by law
  • You only re-serve on a genuine upgrade

    You only re-serve a waiting period on a genuine upgrade — 12 months for pre-existing conditions on newly added categories, two months for most others.

  • Your Lifetime Health Cover status travels with you

    Your Lifetime Health Cover status travels with you. Switching never resets or increases it.

    Protected by law
  • Extras limits reset on the new policy's cycle

    Extras limits reset on the new policy's cycle, so timing a switch after a big dental or optical claim is worth a moment's thought.

  • We check your hospital first

    We confirm your private hospital is in the new fund's agreement network before anything is signed.

    Protected by law

Free tool

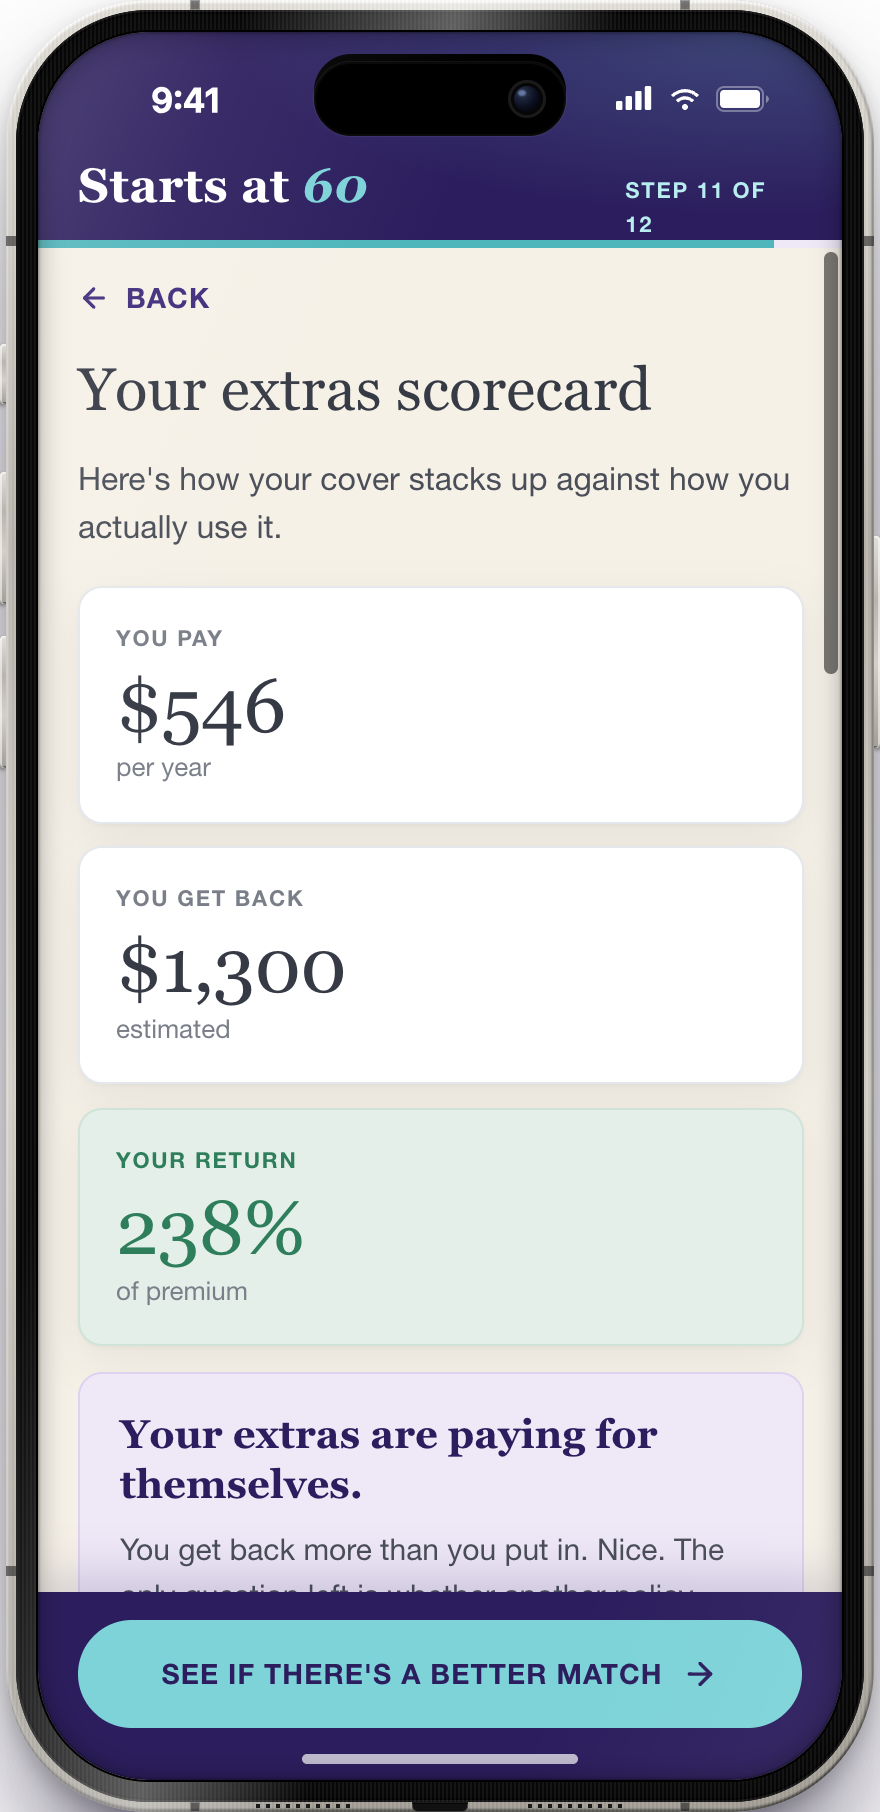
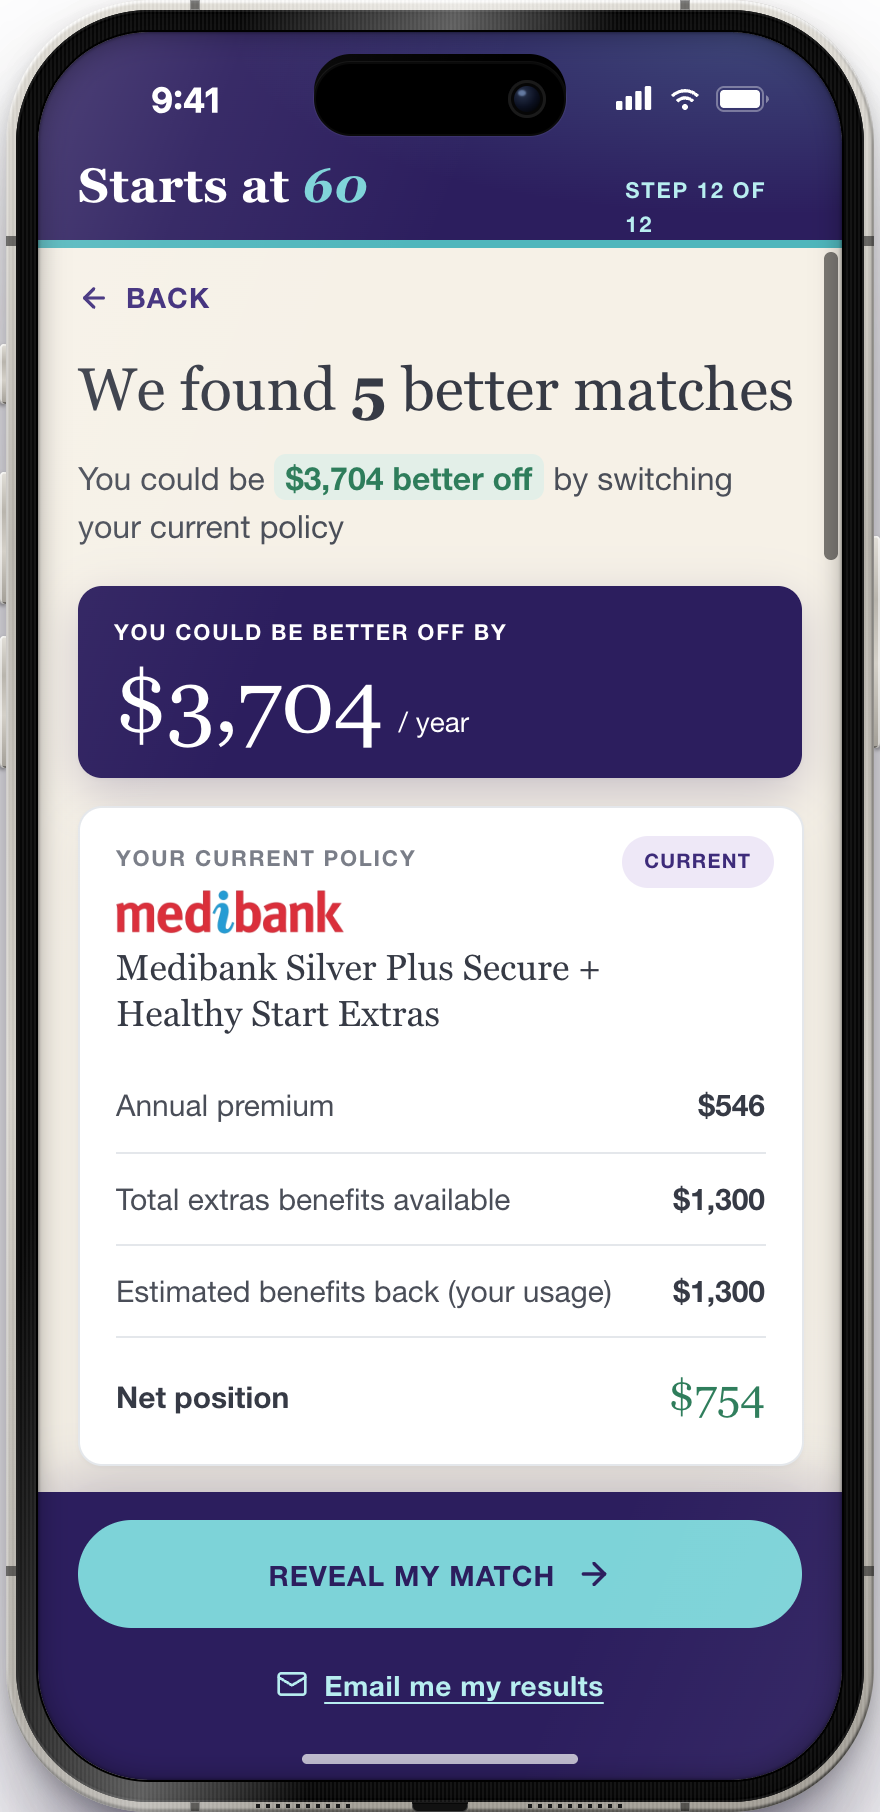
Is your extras cover paying for itself?

Dental, glasses, physio, hearing aids — add up what you actually claimed last year and see it against what you paid in. Five minutes, no policy documents needed.

Extras scorecard showing what you pay, what you get back and your annual returnExtras better-matches screen showing potential annual savings

Ready to find out where you stand?

Two minutes of questions, one 15-minute call, and an honest answer. Free, no obligation, and a $100 gift card if you switch.*

Over 60s: the questions we hear most

Do premiums go up just because I've turned 60?

No. Health insurance in Australia is community rated, so a fund cannot charge you more or refuse you cover because of your age or health. What changes with age is the government rebate: today it steps up at 65 and again at 70, which lowers what you pay. From 1 April 2027 the government has proposed removing that age-based increase, so from then the same policy will cost more for people over 65. It's a good reason to compare before it lands.

Is Gold hospital cover worth it at my age?

It depends on what you want protected. Gold is the only tier that must cover joint replacements, cataract surgery, dialysis and weight-loss surgery — the procedures most likely to matter after 60. If those are on your radar, Gold is usually the honest answer. If they are not, Silver Plus can cover almost everything else for meaningfully less.

I've had my policy for 15 years. Will I have to re-serve waiting periods if I switch?

Not for anything you're already covered for at the same or a lower level. Funds must recognise the waiting periods you've already served. You only serve new waiting periods on benefits you're upgrading into — for example moving from Silver to Gold for joint replacements.

What happens to my Lifetime Health Cover loading?

If you held hospital cover continuously for 10 years after first taking it out, any LHC loading is removed permanently. If you still carry a loading, it moves with you when you switch funds — switching neither adds to it nor resets it.

Can I keep my specialist and my hospital if I change funds?

Your specialist choice comes from having hospital cover at the right tier, not from the fund. What can change is which private hospitals have an agreement with your new fund. We check your hospital before you switch — it takes us one call.

Should I drop extras to save money?

Look at what you actually claimed last year. If your dental, optical and physio claims are less than what extras cost you, a leaner extras policy or none at all can be the right call. We'll show you the numbers rather than talk you into a bundle.

How does the $100 gift card work?

If you're a Starts at 60 member and you switch to a new hospital and extras policy through this service, you'll receive a $100 gift card once your new policy is confirmed. Full terms and conditions, including timing and eligibility, are on our offer terms page.

Is Starts at 60 a health insurer? Who am I actually dealing with?

No. Starts at 60 doesn't arrange, issue or advise on health insurance. The comparison service on this site is provided by Comparify (ABN 78 665 886 644), a member of the Private Health Insurance Intermediaries Code of Conduct. Comparify's advisors compare the funds and handle any application you choose to make — and Starts at 60 is paid a referral fee by Comparify if you switch, which never changes the price you pay.

Comparison service provided by Comparify, a PHII Code member. See the footer for full details.

© 2026 Starts at 60. Comparison service by Comparify.